A Bayesian Time Series Analysis of Annual Inflation Growth Percent in Egypt
DOI:
https://doi.org/10.64060/JASRv2i42Keywords:
Autoregressive moving average processes, Bayesian time series analysis, Inflation rates, Mean absolute error, Mean absolute percentage errorAbstract
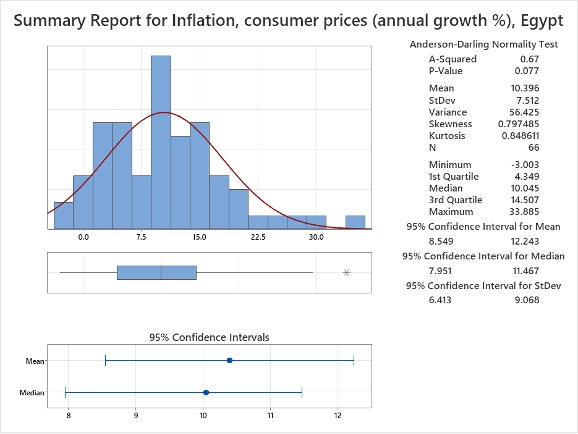
The current manuscript aims to employ the Bayesian approach to analyze a real data time series in order to understand its functional form and give accurate forecasts for its future observations. The time series considered in the study is the data set of annual inflation growth percent in Egypt during the period from 1960 to 2025. The series is modeled and its observations are predicted using a Bayesian approach. Some accuracy measures are used such as Root mean squared error (RMSE), mean absolute error (MAE) and mean absolute percentage error (MAPE). The results showed that, ARIMA(1,1,1) model is fitted by the proposed Bayesian technique and passes all the diagnostic checking tests and can be used efficiently in the forecasting process. The model was used to give point and interval forecasts for the succeeding three years.
References
Abraham, B. and Ledolter, J. (1983). Statistical Methods for Forecasting. John Wiely and Sons Inc. New York.
Albassam, M.S., Soliman E.E.A. and Ali, S.S. (2023). An Effectiveness Study of the Bayesian Inference with Multivariate Autoregressive Moving Average Processes. Communications in statistics- Simulation and Computation. 52(10):4773-4788. https://doi.org/10.1080/ 03610918.2021.1967986.
Albert, J. and Chib, S. (1993). Bayesian Inference via Gibbs Sampling of Autoregressive Time Series Subject to Markov Mean and Variance Shifts. Journal of Business and Economic Statistics, 11(1):1-15.
Ali, S.S. (2015). Bayesian Forecasting Of Vector Moving Average Processes. . The Egyptian Statistical Journal, 59(1):68-89. https://doi.org/10.21608/ESJU.2015.314457.
Amin, A. (2019). Gibbs Sampling for Bayesian Prediction of SARMA Processes. Pakistan Journal of Statistics and Operation Research. 15(2):483-499. https://doi.org/10.18187/ pjsor.v15i2.2174.
Barnett, G., Kohan, R. and Sheather, S. (1995). Markov Chain Carlo Estimation of Autoregressive Models with Application to Metal Pollutant Concentration in Sludge. Mathematical and Computational Modeling, 22(1):7-13.
Bowerman, B. and O'Connell (1987). Time Series Forecasting: Unified Concepts and Computer Implementation. Boston: PWS Publishers Dexbury Press.
Box, G. and Jenkins, G. (1970). Time Series Analysis: Forecasting and Control. Holden-Day, San Francisco.
Box, G., Jenkins, G., Reinsel, G. and Ljung, M. (2016). Time series analysis: Forecasting and control. 5th ed. Hoboken, NJ: John Wiley & Sons.
Broemling, L. (1985). Bayesian Analysis of Linear Models. Marcel Inc., New York.
Broemeling, L., Shaarawy, S. (1988). Time series: A Bayesian analysis in time domain: Bayesian Analysis of Time Series and Dynamic Models. Studies in Bayesian Analysis of Time Series and Dynamic Models, Edited by J. spall, Marcel Dekker Inc., New York:1–22.
Chatfield, C. (1980). The Analysis of Time Series: Theory and Practice. Chapman and Hall Ltd., London.
Chatfield, C. (2019). The analysis of time series: Theory and practice. An introduction with R, 7th ed. Boca Raton, FL: Chapman & Hall.
Chen, C. (1992). Bayesian Inferences and Forecasting in Bilinear Time Series Models. Communication in Statistics – Theory and Methods, 21(6):1725-1743. https://doi.org/10.1080/03610929208830875.
Chib, S. (1993). Bayes Regression with Autoregressive errors. Journal of Econometrics, 63(3):275-294.
Chib, S. and Greenberg, E. (1994). Bayes Inference in Regression Models With ARMA(p,q) Errors. Journal of Econometrics, 64(1):183-206.
Chow, G. (1975). Multi-period Prediction from Stochastic Difference Equations by Bayesian Methods .Chapter 8 of Studies in Bayesian Econometrics and Statistics , edited by S.E. Fienberg and A. Zellner. North-Holland, Amsterdam.
De Alba, E. (1993). Constrained Forecasting in Autoregressive Time Series Models: Bayesian Analysis, International Journal of Forecasting, 9(1):95-108.
Diaz, J. and Farah, J. (1981). Bayesian Identification of Autoregressive Process. Presented at the 22nd NBER-NSF Seminar on Bayesian Inference in Econometrics.
Elnagger, A., & Richter, C. (2022). Exchange rate pass-through, inflation, and monetary policy in Egypt. Applied Economics Quarterly, 68(1):1–36. https://doi.org/10.3790/aeq.68.1.1.
El-Sheikh, A. A. and Kandil, S. M. (2016). Time Series Analysis of Inflation in Egypt. Presented at the 48th Annual Conference on Statistics, Computer Science and Operation Research, Institute of Statistical Studies and Research, Cairo University.
Granger, C. and Newbold, P. (1977) .Forecasting Economic Time Series. Academic Press, New York.
Greenlaw, S. A., Shapiro, D., & MacDonald, D. (2026). Principles of economics. 3rd edition, OpenStax, (an initiative of Rice University).
Harison, P. and Stevens, C. (1976). Bayesian Forecasting (with discussion). Journal of the Royal Statistical Society, Series B, 38(2):205-242.
Harvey, A. (1981). Time Series Models. Wiley, New York.
Lahif, M. (1980). Time Series Forecasting with non-informative Prior Distribution. Technical Report No. 111, Department of Statistics, University of Chicago.
Liu, L. (2009), Time Series Analysis and Forecasting. 2nd edition. Scientific Computing Association Corp, USA.
Marriott, J., Ravishanker, N., Gelfand, A. and Pai, J. (1996). Bayesian Analysis of ARMA Processes: Complete Sampling based Inference under Full Likelihoods, In Bayesian Statistics and Econometrics, edited by Zellner, A., Berry, D., Chaloner, K. and Geweke, J., John Wiley & Sons, Inc., New york.
Monahan, J. F. (1983). Fully Bayesian analysis of ARIMA time series models. Journal of Econometrics, 21(3):307–331. https://doi.org/10.1016/0304-4076(83)90048-9.
Newbold, P. (1973). Bayesian Estimation of Box and Jenkins Transfer Function Model for Noise Models .Journal of the Royal Statistical Society , Series B, 35(2):323-336.
Omar, M.A., Shahin, S.E. and Roshdy, M. (2022). Forecasting Inflation in Egypt (2019-2022) by using AutoRegressive Integrated Moving Average (ARIMA) Models. Journal of Advanced Veterinary Research, 12(6):670–676.
Philippe, A. (2006). Bayesian Analysis of Autoregressive Moving Average Processes with Unknown Orders .Computational Statistics & Data Analysis, 51(3): 1904-1923. https://doi.org/10.1016/j.csda.2005.12.005.
Priestley, M. (1981). Spectral Analysis of Time Series, Academic Press, London.
Romer, D. (2018). Advanced Macroeconomics. 5th edition, McGraw-Hill Education.
Shaarawy, S. and Ali, S. (2003). Bayesian Identification of Seasonal Autoregressive Models. Communications in Statistics-Theory and Methods, 32(5):1067-1084. https://doi.org/10.1081/STA-120019963.
Shaarawy, S., Ali, S. (2008). Bayesian identification of multivariate autoregressive processes. Communications in Statistics—Theory and Methods, 37(5):791–802. https://doi.org/10.1080/ 03610920701504370.
Shaarawy, S. and Ali, S. (2015). Bayesian Identification of Seasonal Multivariate Autoregressive Processes. Communications in Statistics—Theory and Methods, 44(4): 823–836. https://doi.org/10.1080/03610926.2012.752850.
Shaarawy, S. and Broemeling, L. (1984). Bayesian Inference and Forecasts with Moving Average Processes. Communications in Statistics-Theory and Methods, 13(15):1871-1888. https://doi.org/10.1080/03610928408828800.
Shaarawy, S. and EL-Shawadfy, G. (1994). On the Adequacy of Using T Approximation in Bayesian Inferences of ARMA Models. The Egyptian Statistical Journal, 43(2):193-208.
Shaarawy, S., Soliman, E. and Ali, S. (2007). Bayesian Identification of Moving Average Models, Communications in Statistics-Theory and Methods, 36(12):2301-2312. https://doi.org/10.1080/03610920701215449.
Shaarawy, S.M. (2023). Bayesian modeling and forecasting of vector autoregressive moving average processes. Communications in Statistics-Theory and Method, 52(11):3795-3815. https://doi.org/ 10.1080/03610926.2021.1980047.
Shaarawy, S.M., Ali, S.S. and Soliman, E.E.A. (2024). Bayesian Identification of Seasonal Vector ARMA Processes. The Egyptian Statistical Journal, 68(2): 129-145. https://doi.org/10.21608/ESJU.2024.318938.1044.
Soliman, E.E.A. (2008). Efficiency of the approximate Bayesian prediction of ARMA models: A simulation study. The Egyptian Statistical Journal, 52(2):56-75. https://doi.org/ 10.21608/ESJU.2008.315419.
Soliman E.E.A. and Ali, S.S. (2026). Assessment of the performance of the Bayesian Forecasting for Vector ARMA Processes. SCOPUA: Journal of Applied Statistical Research. 2(1). https://doi.org/10.64060/JASR.v2i1.2.
Tiao, G. and Box, G. (1981). Modeling Multiple Time Series with Application. Journal of the American Statistical Association, 76(4):802-816. https://doi.org/10.1080/ 01621459.1981.10477728.
Young, K. and Pettit, L. (2006). The Effect of Observations on Bayesian Choice of an Autoregressive Model. Journal of Time Series Analysis, 27(1):41-50. https://doi.org/10.1111/j.1467-9892.2005.00449.x.
Wei, W.W.S. (2005). Time Series Analysis: Univariate and Multivariate Methods. Addison Wesley, Reading, MA.
Zellner, A. (1971). An Introduction to Bayesian Inference in Econometrics. John Wiley and Sons Inc., New York.
Zellner, A. and Reynolds, R. (1978). Bayesian Analysis of ARMA Models. Presented at the Sixteenth Seminar on Bayesian Inference in Econometrics, June 2–3.
Downloads
Published
Issue
Section
License
Copyright (c) 2026 Sherif S. Ali , Emad E. A. Soliman Soliman (Author)

This work is licensed under a Creative Commons Attribution 4.0 International License.
How to Cite